The clock after a loss · Heirs' guide
Reverse Mortgage After Death: What Heirs Must Know, the 30-Day and 6-Month Deadlines, and How to Empty and Sell the House in Time
November 16, 202611 min readSource-checked guide
Reverse mortgage after death: heirs get 30 days to respond, about 6 months to sell, and never owe more than the house is worth. Deadlines, options and next steps.
A reverse mortgage comes due when the last borrower dies. The servicer sends a demand letter, and heirs generally have 30 days to answer it: pay off the loan, sell the house or hand it to the lender. Selling usually gets about 6 months, sometimes longer with approved extensions. Heirs never owe more than the house is worth.
The phone call usually comes a few weeks after the funeral. A letter from a company you have never heard of says your mother's house is "due and payable." The family hadn't even started on the closets.
That letter is about a reverse mortgage, most often a Home Equity Conversion Mortgage (HECM), the federally insured kind most older homeowners have. It doesn't mean the house is lost, and it doesn't mean the family owes money out of pocket. It does mean a clock is running, and the clock is shorter than most probate cases.
This guide explains what the rules actually say, what to do in the first week, the four ways out, and how to get a full house emptied and sold before the deadline. It's general information, checked against the Consumer Financial Protection Bureau, HUD and the reverse mortgage lenders' trade group in November 2026. It is not legal or financial advice. Your loan documents and your servicer's letter control.
The short answer: what happens to a house with a reverse mortgage when the owner dies?
The loan becomes due after the death of the last borrower, or of an eligible non-borrowing spouse. "Once your heirs receive a due and payable notice from the lender, they have 30 days to buy, sell, or turn the home over to the lender to satisfy the debt," the CFPB says, adding that "it might be possible for the timeline to be extended up to six months so your heirs can sell the home or obtain their own loan to purchase the home" (CFPB, last reviewed Aug 2026).
HUD's own heir guide says the lender "may approve 90-day extensions with satisfactory documentation that the estate or heirs are actively trying to sell the property or repay the HECM loan" (HUD). Industry guides describe that as up to two 90-day extensions, for roughly a year in total (mortgagereversal.co, reviewed Oct 2026).
Do heirs have to pay back a reverse mortgage out of pocket?
No. A HECM is a non-recourse loan. The debt is paid from the house, not from the heirs' own money. If the loan is bigger than the house is worth, the CFPB says "your heirs won't have to pay more than 95 percent of the appraised value. The remaining balance of the loan is covered by mortgage insurance" (CFPB).
Is there a co-borrower or a surviving spouse?
Check this first, because it can stop the clock entirely. If a co-borrower is on the loan, they can stay and keep receiving the loan's benefits as long as they meet its terms. A spouse who isn't on the loan may be able to stay if they qualify as an Eligible Non-Borrowing Spouse under HUD rules (CFPB). Call the servicer and ask, in writing, whose names are on the loan.
Reverse mortgage deadlines for heirs: the timeline
The dates below are how the official sources describe the process. Use the planner to turn them into real calendar dates, then confirm every one with the servicer.
Deadline planner
Put your real dates on the calendar
- 1
Letter + 30 days
Answer the demand letter
Pay off, say you intend to sell, or offer a deed-in-lieu. Some states allow 45 days.
- 2
About 6 months
Sale or payoff target
The usual window to sell or refinance when the estate is actively working on it.
- 3
+ 90 days
First extension, if approved
Needs proof: a listing agreement, a sales contract or loan approval. Not automatic.
- 4
+ 90 more days
Second extension, if approved
About 12 months is the outer limit. Slow probate alone usually isn't enough.
Estimates for planning only, not legal advice. Your servicer's letter sets the real deadlines. Sources: CFPB, HUD, NRMLA. Checked Nov 2026.
| Step | What happens | Typical timing |
|---|---|---|
| Death of last borrower | Loan becomes due; no more money can be drawn | Day 0 |
| Demand letter | Servicer must send a HUD-required letter to the property and known heirs | Soon after the servicer learns of the death |
| Respond | Pay off, state intent to sell, or offer a deed-in-lieu | 30 days from the letter (45 in some states) |
| Sell or refinance | Time to market the house or get a new loan | About 6 months from death |
| Extensions | Up to two 90-day extensions, only with proof of progress | Up to about 12 months |
| Foreclosure | Servicer must start it if nothing is resolved | Timing set by HUD and state law |
The trade group's servicing column explains why servicers can't simply wait: "there are strict HUD timelines they must meet," and servicers "must achieve the first legal foreclosure action on or before six months after the last borrower's death" unless an extension applies (NRMLA, Aug 2024). The same column notes the estate has "30 days, or 45 days in some states, from the date of the Demand Letter to satisfy the debt or provide a letter of intent."
Is probate a good enough reason for an extension?
Not on its own. Extensions are tied to evidence that someone is actively selling or refinancing, such as a listing agreement, a signed contract or a loan application. Waiting on probate, with no listing or loan in progress, is hard to show as progress. If probate is slow, talk to the probate attorney about getting the executor authority to list the house early.
The first seven days: a checklist
- Find the loan paperwork. Monthly or annual reverse mortgage statements name the servicer and loan number.
- Call the servicer and report the death. Ask for the payoff amount, the response deadline and how to submit a letter of intent. Write down the name of everyone you speak to.
- Send the death certificate and any proof of who is handling the estate, such as letters testamentary.
- Tell them your plan in writing before the 30-day deadline, even if the plan is "we intend to sell."
- Keep insurance and taxes current. HUD says "property taxes and insurance on the property remain the responsibility of the borrower's estate until title is transferred" (HUD). Tell the insurer the house is vacant; many policies change when nobody lives there.
- Secure the house. Change the locks if needed, remove valuables and medications, keep the heat or water on to prevent damage.
- Call a HUD-approved housing counselor. Counseling is free: 800-569-4287 or HUD's counselor finder.
Your four options: sell, keep, the 95% rule, or deed-in-lieu
Every family ends up in one of four places. Pick the one that matches your situation to see how it works and what to watch for.
The four ways out
Which one fits your family?
- Fits when
- The house is worth more than the loan, and nobody wants to live there.
- How it works
- List it, sell it, and the loan is paid from closing. The heirs keep what's left.
- Watch for
- Empty and clean it first. An estate sale can do both and add cash to the estate.
Can I keep my parent's house with a reverse mortgage?
Yes, if you pay off the full loan balance. HUD's guide is direct: "If you prefer to keep the home instead of selling it, the HECM loan balance must be paid off in full" (HUD). Most heirs do this with a new mortgage in their own name. Start the application in the first week, because the approval timeline is the hardest part.
What if the house is worth less than the reverse mortgage?
Then the 95% rule applies. "If the loan balance is more than the home is worth, the estate or heirs may sell the home for at least 95-percent of the current appraised value and the lender will accept the net proceeds as satisfaction of the loan" (HUD). The CFPB adds that heirs who want to keep an underwater house can generally buy it for that same 95% figure.
What is "cash for keys" on a reverse mortgage?
If the family signs the house over through a deed-in-lieu of foreclosure, some servicers offer a payment for leaving it empty and in good condition by an agreed date. NRMLA's column notes "Cash for Keys may also be available." Ask before you sign, get the terms in writing, and take out anything the family wants first, because whatever stays may be cleared out.
A worked example: equity vs. underwater
Diagram · illustrative numbers
House A: has equity
Sell for $250,000 → loan paid → about $100,000 to the estate, before selling costs.
House B: underwater
Loan $300,000, appraisal $200,000 → sell for at least $190,000 (95%). Insurance covers the gap.
These are made-up numbers to show the math, not a prediction for any house. In House A, the family sells, the servicer is paid from closing, and the leftover equity goes to the estate after commissions and closing costs. In House B, the loan grew past the value, so the family only needs a sale of at least 95% of the appraisal. Neither family writes a check for the difference.
Notice what both have in common: the house still has to be emptied. In House A, every week of delay is interest and costs taken from the heirs' share, because a reverse mortgage balance keeps growing until it's paid. In House B, the deadline is the main risk.
Why an empty house sells faster
Real estate agents will tell you a full house is harder to list, harder to photograph and harder for buyers to picture as theirs. The bigger problem for these families is time: a house full of 40 years of belongings can take weeks to sort, and a reverse mortgage doesn't give you months to spare.
We cover the tradeoffs in whether to hold an estate sale before or after listing the house and selling a house with the furniture still in it. With a reverse mortgage deadline, "before" almost always wins.
Estate sale vs. buyout vs. cleanout when you only have weeks
| Option | Typical timing | Money to the estate | Best when |
|---|---|---|---|
| Estate sale | Usually booked a few weeks out, then a 1–3 day sale | Highest for a full house with sellable contents | There's furniture, collectibles, tools or jewelry worth selling |
| Buyout | Fast: one offer, one pickup | Lower, because the buyer takes the risk | Time is very short or contents are modest |
| Cleanout / junk removal | Fastest | You pay them | Little has resale value, or after the sale is done |
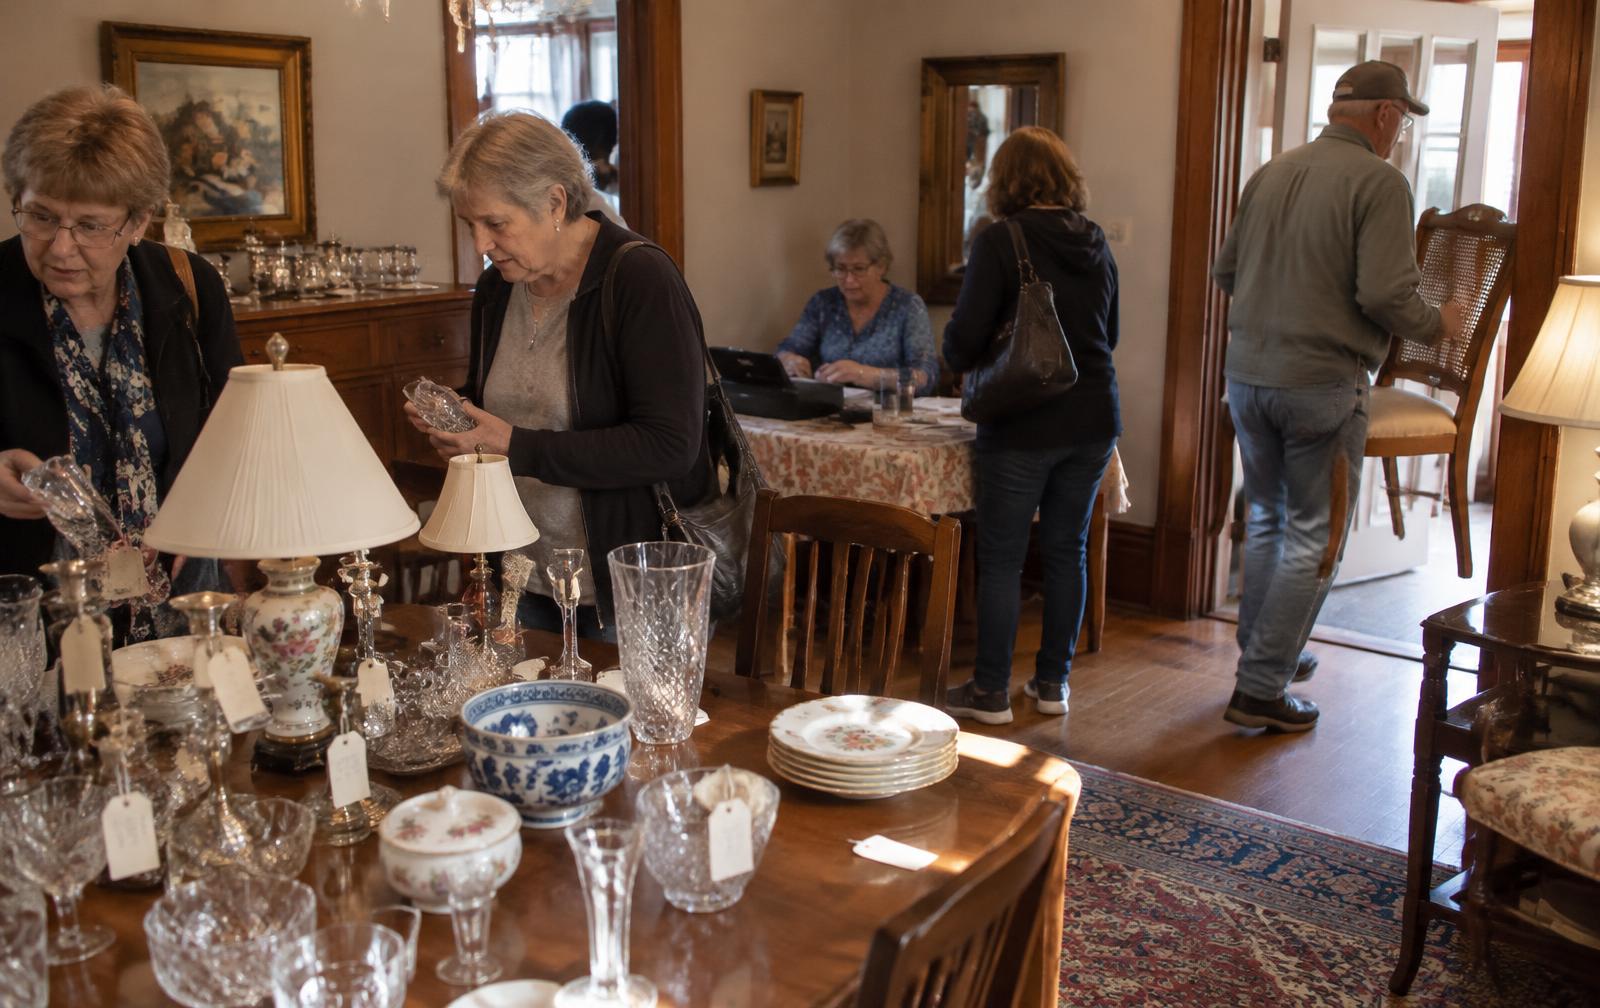
Many families combine them: family picks first, an estate sale sells the rest, and a cleanout crew handles leftovers so the house is broom-clean for the agent. See estate sale vs. buyout and how long an estate sale takes for the details. When you call companies, tell them about the reverse mortgage deadline up front; good companies will say honestly whether they can fit it.
Can we hold an estate sale before the reverse mortgage is paid off?
Generally yes. The loan is secured by the house, not the furniture inside it, and selling the contents is a normal step before selling a house. The person running the sale should have legal authority over the estate, which may require the probate court's letters first. Our guide to estate sales during probate covers who can sign. If you're unsure, ask the estate's attorney before you sign a contract.
Who to call, in order
- The reverse mortgage servicer: deadlines, payoff, appraisal and extensions.
- A HUD-approved housing counselor: free, neutral help with options.
- A probate or estate attorney: authority to sell, and anything involving the will.
- A real estate agent who has sold reverse mortgage houses: they know the appraisal and paperwork.
- An estate sale company: to empty the house and turn the contents into money. Find one near the house.
Realtors and attorneys who send families to estate sale companies can find a working process in our realtor's guide to estate sales. Families just starting should read what to do after a death.
Costly mistakes heirs make
- Ignoring the first letter. Silence is the fastest path to foreclosure. Answer within 30 days, even with an incomplete plan.
- Letting the insurance lapse. A vacant, uninsured house is a disaster waiting for a burst pipe, and the estate owes the premiums until title transfers.
- Waiting for probate to finish before doing anything. Order the appraisal, book companies and gather paperwork in parallel.
- Assuming you owe the full balance on an underwater house. You don't. Ask about the 95% rule.
- Signing a deed-in-lieu with family items still inside. Empty it first, or agree in writing on what stays.
- Paying for a quick "we buy houses" offer without comparing. If there's equity, that equity belongs to the heirs.
Questions & answers
Frequently asked questions
Do heirs have to pay back a reverse mortgage?
The loan has to be repaid, but from the house, not from the heirs' own money. Heirs who want the house pay off the balance. Heirs who don't can sell it, and if the loan is larger than the value, a sale at 95% of the appraised value settles a HECM.
How long do heirs have after a reverse mortgage borrower dies?
About 30 days after the demand letter to respond, usually about 6 months to sell or refinance, and up to two 90-day extensions with proof that you are actively selling or financing. Confirm the dates for your loan with the servicer.
What if the house is worth less than the reverse mortgage?
For a HECM, sell it for at least 95% of the current appraised value, and FHA insurance covers the rest. The heirs don't owe the difference.
Can I keep my parent's house?
Yes, by paying the full loan balance, usually with your own mortgage. If the balance is higher than the value, the CFPB says heirs can generally buy it for 95% of the appraised value.
Can we hold an estate sale before the reverse mortgage is paid off?
Usually yes, as long as the person running it has authority over the estate. Emptying the house first typically helps it sell faster.
Who pays property taxes and insurance after the death?
The estate does, until the title transfers. Keep both current and tell the insurer the house is vacant.
What is "cash for keys"?
A payment some servicers offer when the family signs the house over by deed-in-lieu and leaves it empty and clean by a set date. Ask for the terms in writing.
Checked against the CFPB, HUD and NRMLA in November 2026. This is general information, not legal or financial advice. Rules differ for proprietary (non-HECM) reverse mortgages; ask your servicer which kind you have.
Keep exploring
Get the house emptied before the deadline
Tell local estate sale companies about the reverse mortgage timeline up front, so they can say honestly whether they can fit it.
Find an Estate Sale Company
About the author
Andy
Founder, EstateSaleFinder.net
Hi, I'm Andy — a retired commercial photographer turned developer with a five-year (and counting) obsession with estate sales. I started EstateSaleFinder.net because I knew there had to be an easier, smarter way to find and list estate sales. Now I get to chase treasure and build the tool I always wished existed.